
 rahulNovember 13, 20264 Mins read0
While the proportion of seriously overdue loans remains relatively small, warnings from credit bureau TransUnion Cibil and lenders such as Bajaj Finance and Piramal Finance have given a worrying sign — that some borrowers may be using fresh loans against gold to manage existing debt rather than finance new needs.
Also read | Indians splurge ₹72,000 crore on their favourite golden obsession to satisfy festive craving
The development has stoked concerns about the quality and sustainability of growth in one of India’s fastest-expanding retail credit segments, a ToI report said on November 13.
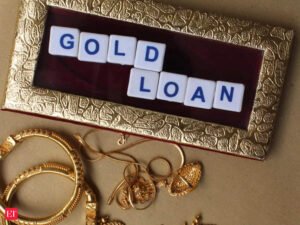
Gold has long been India’s favourite financial cushion — a store of wealth that households can turn to whenever money is short. But as Indians increasingly pledge their jewellery to get cash, a troubling question may have emerged: is the glittering gold loan boom also hiding a growing debt problem?
The speed and scale of the expansion in India’s gold loan market are striking.
Outstanding gold loans reached a record Rs 22.5 lakh crore in August 2026, almost thrice the levels of August 2023. However, even as the expansion continued, the rise in overdue accounts began to draw attention too.
 ET Online
Loans overdue for more than 90 days went up from 0.2% of the portfolio in March to 0.3% in August. While the absolute level was low, the near doubling in just five months made policymakers sit up and take notice.
The expansion has also changed the character of the market. TransUnion Cibil data showed that lenders sanctioned gold loans worth Rs 8.2 lakh crore in the April-June quarter, a 12% increase year-on-year, even as the number of loans originated fell 15% to 3.7 crore.
The number of unique borrowers remained broadly stable at 2.4 crore. The indication may be that growth in lending value is increasingly coming from larger loans rather than a comparable increase in the number of customers.
More worrying could be the possibility that gold loans are becoming a means of dealing with distress.
Macquarie Capital has warned that some lenders may be extending fresh gold-backed loans to people already badly overdue on other loans. It means that instead of addressing the underlying cash-flow problem, such transactions could simply move outstanding debt from one financial institution to another.
Also read | India’s gem and jewellery exports jump 34% to $2.92 billion in October on festive demand
The scale of the overlap is significant. According to Piramal Finance managing director and CEO Jairam Sridharan, an estimated 15-23% of gross gold loan disbursements across the industry during FY26 went to borrowers who were already more than 90 days overdue on at least one other loan.
ET OnlineSridharan estimated the value of these disbursements at Rs 4.7 lakh crore.
Bajaj Finance reported an increase in early repayment stress in its gold loan portfolio. Its data showed that assets classified under Stage 2 and Stage 3, reflecting loans overdue by more than 30 days, increased 15 basis points quarter-on-quarter in the July-September quarter.
A substantial part of this stress was attributed to short-tenure gold loans. The company has since discontinued these offerings, it said, moving instead towards longer repayment periods that give borrowers more flexibility.
Piramal Finance flagged the possibility of overlapping gold borrowings too, saying that nearly 35% of its customers had gold loans from another financial institution.
Macquarie has cautioned that collections teams at some lenders could be encouraging borrowers with overdue accounts to pledge jewellery elsewhere and use the proceeds to settle existing dues.
Such practices could make reported repayment performance look healthier without necessarily improving borrowers’ finances, Reuters reported in late October.
The lure of gold loans is not hard to understand. Unlike unsecured personal loans, they are backed by an asset that lenders can auction to recover their money.
Rising gold prices have also boosted the borrowing capacity of people without requiring them to sell family jewellery. For lenders, this makes for a chance to expand credit with tangible security.
But collateral does not necessarily mean repayment capacity in all cases.
A borrower who pledges jewellery to get money for closing an overdue personal loan may have bought time, not stability. If the underlying income problem continues, the borrower might later default on the gold loan as well. This will put her family assets at risk.
There is another vulnerability as well. A sharp fall in gold prices, combined with rising defaults, will weaken the lenders’ position substantially, because a fall in collateral value will shrink the cushion.
If defaults rise at the same time as gold prices fall, lenders will likely be left staring at having to auction large quantities of gold in an unfavourable market.
There is another new side to this risk: rising competition.
As banks and NBFCs seek growth beyond conventional unsecured credit, they are increasingly being drawn to gold-backed lending. Established, specialised gold loan players have years of experience in valuing jewellery, monitoring collateral and carrying out auctions. The new players must develop these strong points while competing for market share at the same time.
ET OnlineThe RBI’s revised lending rules (effective April 1, 2026) have also changed the game. They provide for loan-to-value limits of up to 85% for eligible gold loans of up to Rs 2.5 lakh, 80% for loans above Rs 2.5 lakh and up to Rs 5 lakh, and 75% for larger loans. Consumption-focused bullet-repayment loans are also subject to a maximum tenure of 12 months.
While these safeguards are important, the real test is in assessing borrowers’ overall financial health rather than relying predominantly on the value of their jewellery, at ET report says.
One must note here that a gold loan used for productive investment or a genuine emergency is very different from one taken to postpone default on another obligation.
As of now, the bottomline seems to be that while India’s gold loan market is shining, the sharp rise in serious delinquencies can be a reminder that trouble could be brewing under all that glitter.