
 rahulNovember 15, 20262 Mins read0
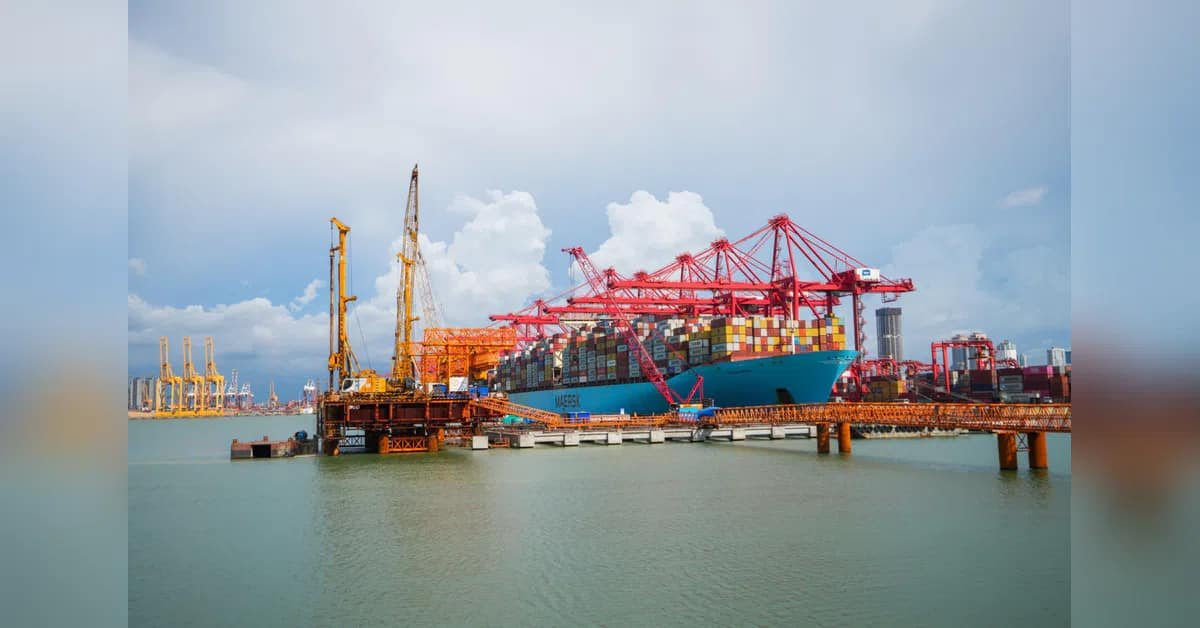
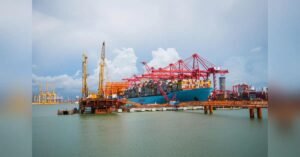
Steady performance in the September quarter despite geographical disruptions, expansion of operations through acquisitions and strong growth prospects are positives for the country’s largest port operator, Adani Ports and Special Economic Zone (APSEZ). These triggers led to upgrades by some brokerages, and the stock hit an all-time high of ₹1,979 on November 11.
Earlier this month, APSEZ acquired Evos BV, Europe’s second-largest independent liquid storage operator. This is expected to strengthen its presence in European energy hubs, diversify its earnings base and expand its exposure to high-value liquid storage and sustainable fuels.
Following the September-quarter results, most brokerages have increased their earnings estimates on expectations that the company will sustain double-digit growth on the back of capacity expansion, network integration and overseas growth.
At the current price of ₹1,904, the stock, which has gained 26.9 per cent over the past year, is trading at about 22 times its FY28 earnings estimates.
The near-term trigger is the acquisition of a 100 per cent stake in Netherlands-based Evos from Igneo Infrastructure Partners at an enterprise value of €2.56 billion. This values it at 11.7 times calendar year 2025 (CY25) enterprise value to operating profit.
The acquisition will expand APSEZ’s global footprint from 20 to 28 ports and terminals across 10 countries, while more than doubling its liquid storage capacity.
Evos adds a high-margin, cash-generative business, with a 56 per cent earnings before interest, tax, depreciation and amortisation (Ebitda) margin, compared with APSEZ’s 44.8 per cent international ports margin, and an 83 per cent Ebitda-to-cash-flow-from-operations conversion rate.
Management expects cash conversion to be sustained and indicated a double-digit net profit contribution relative to revenue.
Analysts led by Tushar Chaudhari of PL Capital view the acquisition positively, given Evos’ high-margin operations and strategic presence across key European energy hubs.
The addition of Evos should strengthen APSEZ’s international earnings contribution and improve its international ports margin profile, while providing opportunities for growth through higher-value products, operating efficiencies and capacity additions in the future, they added.
While the ports major has demonstrated strong execution capabilities across its domestic acquisitions, its ability to replicate these improvements in mature, high-cost European markets remains to be seen.
The brokerage has a ‘buy’ rating with a target price of ₹2,248.
With €1.43 billion in gross debt, net debt of €1.37 billion and leverage of six times, APSEZ plans balance-sheet restructuring through euro-denominated borrowings, potentially lowering funding costs (4.5 per cent for Evos versus 6.4-6.6 per cent for APSEZ), while providing a natural currency hedge.
Elara Securities believes that financing costs, debt restructuring and sustained cash conversion will be key to realising net profit and earnings per share accretion.
While analysts led by Ankita Shah are yet to factor the acquisition into their estimates, the transaction enhances visibility on long-term shareholder value creation through the development of a globally diversified, integrated ports and liquid storage platform and energy transition infrastructure.
The brokerage has a ‘buy’ rating and has maintained its estimates while raising its target price to ₹2,432.
The company’s operating performance in the September quarter comfortably beat consensus estimates.
The strong operating profit growth of 23 per cent year-on-year (Y-o-Y), despite the West Asia conflict, was on account of its integrated network, which helped absorb the impact of disruptions while capturing a share of high-margin business.
Management raised its FY27 Ebitda guidance by ₹1,000 crore to ₹26,000-27,000 crore.
The increased thrust on domestic port capital expenditure (capex) for Mundra, Dhamra, Hazira and Vizhinjam are major positives, JM Financial Research pointed out.
Analysts led by Priyankar Biswas have modestly increased their Ebitda estimates for FY27 and FY28 on higher-than-estimated profitability in the international business and at Mundra Port.
The brokerage has upgraded the stock to a ‘buy’ rating with a target price of ₹2,065 and believes that the risk-reward metrics look significantly attractive at this stage.