
In 2024, Christine Goulay, founder and CEO of Sustainabelle Advisory Services, wrote that scaling next-gen materials in fashion was all but inevitable—but only if the industry rallied to move from isolated pilots to mainstream use by fixing broken incentives, standardizing metrics and sharing supply chain risk. Two years later, her updated report found that early commercial relationships have proliferated, but the bar for adoption has also risen: Every brand she surveyed in 2026 rated performance and aesthetics as a very significant obstacle, for example, while every investor said the same of supply chain integration.
The biggest challenge facing today’s second wave of materials science startups like Reju and Syre isn’t so much awareness, Goulay said, as it is conversion. The “real energy” she felt around next-gen materials when she conducted her first survey of nearly 160 brands, innovators, suppliers, investors and supporting organizations still crackles. But it’s now tempered by the “realism” of a world economy beset by geopolitical conflict, surging energy costs and whipsawing tariff decisions.
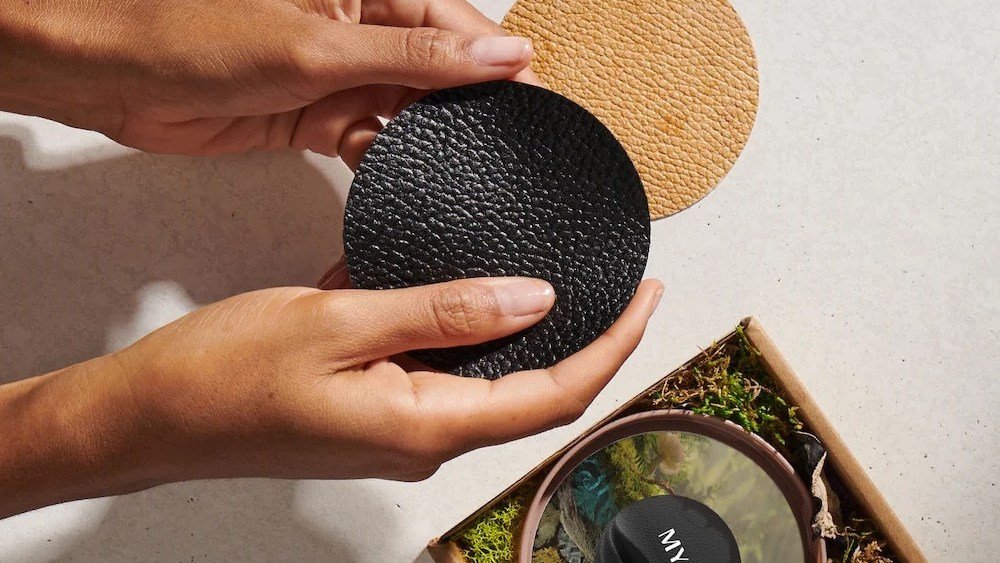
In other words, Goulay said, sustainability is no longer enough for innovators to win the hearts and wallets of brands, as forerunners like Bolt Threads, which stopped producing Mylo, its mycelium-based leather alternative, in 2023, and Renewcell, whose textile-to-textile recycling operations declared bankruptcy in 2024, might have learned the hard way.
“Price parity, equal or better performance and easy implementation are now the starting points,” she said. She cited former PayPal CEO Peter Thiel, who asserts that any new entrant must build a product 10 times better than the dominant solution to overcome customer inertia and switching costs. “This is what we are seeing now. The market is asking innovators to be more rigorous, and many are rising to the challenge,” she added.
After re-surveying the same five stakeholder groups with the same questions, Goulay said she was encouraged to see innovators engaging with the supply chain earlier than they did two years ago. Roughly 81 percent of innovator respondents now have partnerships, pilots or supply agreements with suppliers and manufacturers, up from 64 percent in 2024. Such relationships, she noted, are crucial to success: “A single supplier partnership can accelerate R&D, increase credibility of an innovator’s ability to scale, and reach many brand customers at once.”
But Goulay was also struck by the heightened expectations. All brand respondents rated performance and aesthetics as a very significant barrier, up from 84 percent in 2024—“another sign,” she said, that “compromises for sustainability are no longer tolerated today.” Brands also reported a narrower focus, with interest in recycled polyester holding steady but enthusiasm for bio-based dyes and traceability systems waning the most.
Much of this, she said, is driven by how stretched thin companies have become. In the 2026 survey, only 18 percent of brands rated their internal adoption strategies as “very effective,” a decline from 58 percent in 2024 that they attributed to reduced sustainability budgets and reassigned internal champions. The share of suppliers with funding set aside for material innovation similarly tumbled from 58 percent to 31 percent. And even though the share of innovators with brand letters of intent rose from 48 percent to 72 percent, the share with offtake agreements remained flat at 16 percent, demonstrating that “better market pull through is still needed.”
Supply chain integration also emerged as a common impediment, with the share of investors rating it as a “very significant” obstacle rising from 76 percent to 100 percent. Among suppliers, 62 percent pointed to a lack of brand demand as a major barrier, up from 42 percent, while 69 percent cited difficulty meeting brand performance specifications, up from 58 percent.
“Suppliers are increasingly frustrated, but they are open to partnerships and building internal capability, but brand pull-through is not materializing,” Goulay said.
Still, signs suggest all this momentum is going somewhere. The most frequent request in 2026 was capital for first commercial plants; in 2024, information and standards topped the list. But the same three “silver bullets” identified in 2024 still apply and, if anything, have become more urgent: cultivating internal advocates, aligning procurement KPIs and seasonal calendars with next-gen adoption guidelines and closing the gap between policy intent and operational implementation.
Survey respondents also called for a shorter industrial cycle. Validation, certification and mill integration can take years, but shared pilot facilities and testing infrastructure, regulatory sandbox environments for novel materials and industry alignment on performance specifications—what Goulay termed “better connection infrastructure”—can nudge things forward.
Sustainabelle has synthesized the survey results into a dashboard, available on its website. Alongside it is an industry directory of innovators, suppliers and investors working in material innovation for fashion—a “living resource,” as Goulay described it, for anyone seeking partners, collaborators and ecosystem intelligence.
For Goulay, the findings suggest an industry moving beyond early excitement toward a more grounded phase of growth. She referenced Gartner’s “hype cycle,” a graphical model the business consultancy developed to show how public excitement and commercial expectations for a new technology rise and fall with time. It comprises five distinct phases, beginning with an “innovation trigger,” progressing to a “peak of inflated expectations” and falling into a “trough of disillusionment” before climbing the “slope of enlightenment” to reach the “plateau of productivity.”
“I see the sector in the final moments of the trough of disillusionment, with the slope of enlightenment just ahead, a healthy and realistic position,” Goulay said. “Based on the innovations I am seeing in the market today, this second gen of next-gen is incredibly promising and paving the way toward better market adoption and scale.”