

 rahulNovember 14, 20264 Mins read1
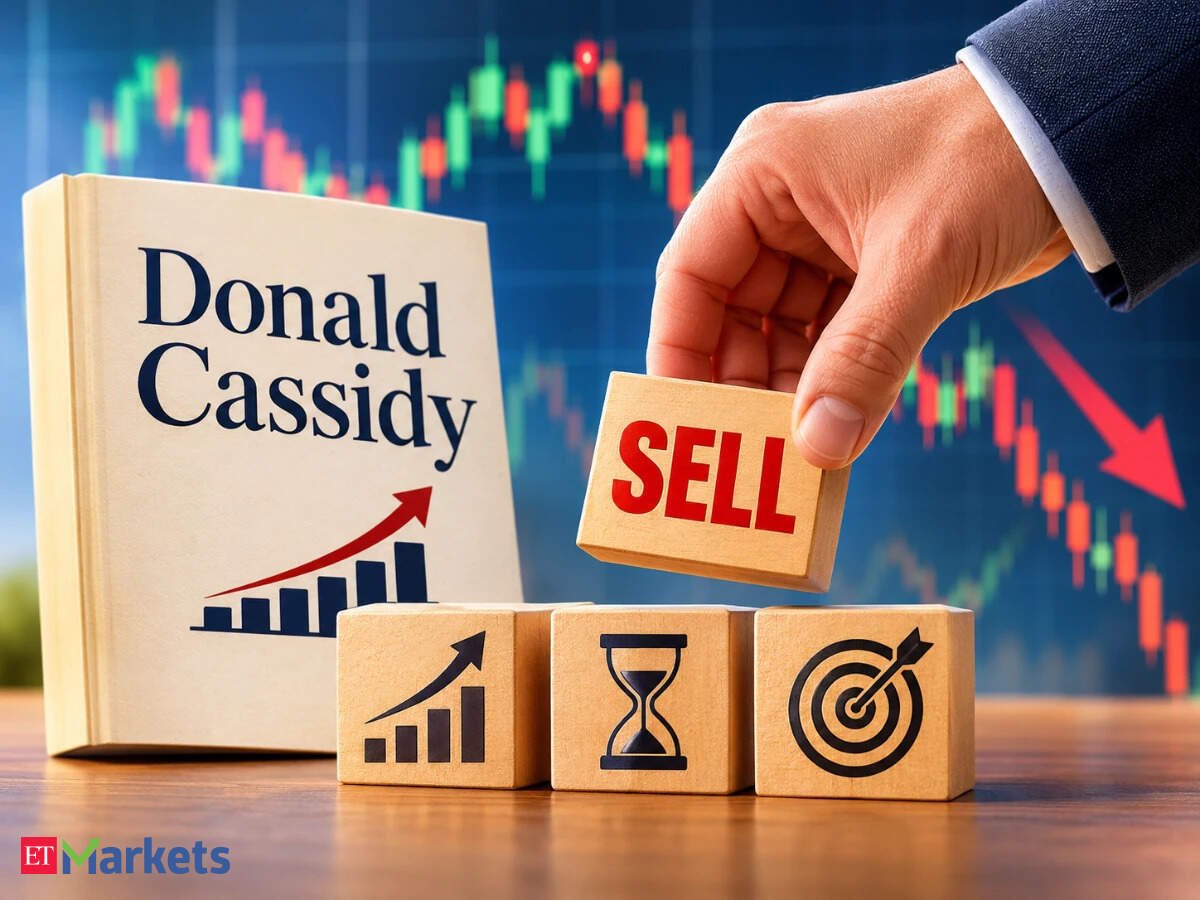
Cassidy argues that investors often underestimate the importance of selling, even though profits are ultimately realised only when shares are offloaded. In his book It’s When You Sell That Counts, he explains how emotional biases, market sentiment and the reluctance to accept losses can prevent investors from making rational exit decisions.
Read more: How to win the investing game? Charles Ellis says make fewer mistakes, focus on long-term goals
Cassidy was a senior research analyst at Lipper Inc. from 1990 to 2006, specialising in mutual funds, closed-end funds, investor psychology and behavioural finance. He has also addressed CFA societies internationally and served on the faculty of Harvard University’s annual congress on the psychology of investing.
According to Cassidy, fear, greed and confusion frequently lead investors to postpone selling decisions. By the time they eventually decide to exit, the opportunity to lock in profits or limit losses may have already passed.
One of the biggest obstacles to profitable selling is investors’ emotional attachment to their holdings. Many investors find it difficult to sell a stock because they fear missing out on further gains or regret exiting an investment that could potentially deliver higher returns.
Cassidy believes investors need to recognise these psychological barriers and develop the discipline to make decisions based on analysis rather than emotions.Following the crowd and adopting a buy-and-hold approach may appear comfortable, but these strategies do not always produce the best outcomes. Investors should evaluate the reasons for holding a stock and prepare arguments both for and against retaining it.
He also advocates contrarian thinking, suggesting that investors should be willing to consider selling when market enthusiasm is excessive and avoid panic selling when markets decline sharply.
Read more: Nicholas Sleep’s investing lessons: Why patience, conviction and long-term thinking matter
Investors often develop strong preferences for companies that have delivered consistent growth and generated substantial returns. However, Cassidy cautions against assuming that successful businesses will continue dominating their industries indefinitely.
Technological advancements, regulatory changes, international competition and shifting market dynamics can weaken even established market leaders.
Companies enjoying strong growth may also command expensive valuations, leaving their shares vulnerable to sharp corrections if business momentum slows or expectations are not met.
Cassidy therefore advises investors to remain alert to changes in a company’s competitive position rather than holding its shares indefinitely simply because it has performed well in the past.
Cassidy believes investors should establish an exit strategy before entering an investment. Buying shares without a clear selling objective can lead to confusion and emotionally driven decisions when market conditions change.
He suggests that an investment target should incorporate three elements: a specific price objective, the business or market scenario expected to drive the stock higher, and a defined time frame.
If the share price reaches the predetermined objective, investors should consider booking profits. Similarly, if the expected developments fail to materialise within the specified period, they should reassess the investment rather than continually extending their holding period.
Cassidy also cautions against buying shares simply because investors admire a company’s management, like its industry or agree with its broader objectives. The investment decision should ultimately be supported by a credible opportunity to generate returns.
Another common investment mistake is holding on to underperforming stocks because of familiarity or emotional attachment.
Cassidy argues that investors should not become loyal to individual stocks when their underlying business prospects deteriorate. Negative developments affecting a company can often be followed by additional challenges, making it important to reassess the investment thesis.
Investors should regularly examine whether a company’s fundamentals, growth prospects and competitive position continue to justify holding its shares.
With thousands of investment opportunities available in the market, capital need not remain locked in stocks that are consistently underperforming.
Cassidy’s broader message is that investors should be prepared to move on from unsuccessful investments and redirect capital towards opportunities with stronger prospects.
Cassidy also encourages investors to understand that stock prices can move in both directions. Limiting investment strategies exclusively to buying shares in anticipation of price increases can restrict the range of opportunities available to market participants.
He highlights short selling as a tool that can potentially help investors benefit when fundamentally overvalued or technically overbought stocks decline.
However, short selling involves significant risks, including potentially unlimited losses if share prices rise sharply. It therefore requires careful risk management and is generally more appropriate for experienced investors.
Cassidy’s broader argument is that investors should avoid developing a one-sided view of the market and should understand how different market conditions can create opportunities as well as risks.
Cassidy believes successful investing requires investors to become as comfortable with selling as they are with buying. Fear of missing further gains, reluctance to acknowledge mistakes and excessive market chatter can all interfere with rational decision-making.
His approach emphasises proactive selling, clearly defined investment objectives and regular reassessment of individual holdings.
Ultimately, identifying a promising stock is only one part of the investment process. Knowing when the original investment thesis no longer holds, when valuations become excessive or when profit targets have been achieved is equally important.
(Disclaimer: This article is based on investment principles discussed by Donald Cassidy in his book, “It’s When You Sell That Counts”. These are general investment insights and should not be treated as individual investment advice.)